Келли критерие һәм рулетка
Келли критерие өстенлеге булган уенчыга күпме куярга кирәклеген әйтә. Рулетка өчен ул ачык җавап бирә: бернәрсә дә.
Келли ставкасы = өстенлек / коэффициент. Тискәре өстенлек булганда формула тискәре өлеш кайтара, бу — куймагыз дигәнне аңлата. Критерий тайпылыш эзләүче уенчыларның ставкаларны ни өчен шулай билгеләвен һәм калганнарның ни өчен бюджет буенча билгеләргә тиешлеген аңлау өчен барыбер файдалы.
Критерий
John Kelly (1956) asked how a gambler with a known edge should size bets to maximize long-run growth of the bankrollакчаУен акчасыУен өчен аерып куелган гомуми сумма. Уен акчасы белән идарә итү — аның күпме өлешен бер ставкада һәм бер сессиядә куркыныч астына куярга карар итү.Тулысынча уку →. The answer, for a bet paying b to 1 with win probabilityматематикаИхтималлыкНәтиҗәнең мөмкинлеге, 0 дән 1 гә кадәр яки 0% тан 100% ка кадәр. Бер сан: 1/37 = 2,70%.Тулысынча уку → p and loss probability q = 1 − p, is to stake the fraction f* = (bp − q) / b of the bankroll. Positive f* means bet that fraction; zero or negative means do not bet. Kelly worked at Bell Labs, and his paper, “A new interpretation of information rate”, set the problem in Claude Shannon’s theory of information: a gambler who gets tips over a noisy line, at fair odds, can grow the bankroll at best at the rate the line carries information. This is a growth objective under a probability model, not a promise to finish ahead after a particular number of bets. A spending limit, finite deadline or payoutакчаТүләүОткан ставка кайтара торган сумма, кире кайтарылган ставкага өстәп «X гә 1» дип күрсәтелә.Тулысынча уку → cap changes the decision problem.
Рулеткада Келли буенча кую
For redставкаКызыл18 кызыл санга тигез түләүле ставка. Французча: rouge.Тулысынча уку →: b = 1, p = 18/37, q = 19/37; f* = (18/37 − 19/37)/1 = −1/37. For a straight upставкаБер санга ставкаБер сан, 35:1 түли.Тулысынча уку →: b = 35, p = 1/37, q = 36/37; f* = (35/37 − 36/37)/35 = −1/1295. Every standard bet gives a negative Kelly fraction, because every bet has a negative edge, and the growth-optimal stake is zero. Kelly betting on roulette is a formal way of saying what the house-edge page says: no positive stake maximizes expected logarithmic growth when the bet has negative expectation. A particular session can still end in profit. La partageкагыйдәLa partageФранцуз кагыйдәсе: нуль чыкканда тигез түләүле ставканың яртысы кире кайтарыла. Бу ставкаларда казино өстенлеген ике тапкыр, 1,35% ка кадәр киметә.Тулысынча уку → needs a separate three-outcome calculation: a win, a full loss or a half-loss on zeroтәгәрмәчНульТигез түләүле, дюжина яки баганага бер ставка да капламый торган бердәнбер яшел уяч; казино өстенлегенең чыганагы. Шулай ук: бер нуль, 0.Тулысынча уку →. Its expected log growth also falls as the stake increases from zero.
Келли кайда кулланылган
Suppose a pocketҗиһазУячРоторда номерланган 37 бүлекнең берсе. Шулай ук: ячейка, касәчек.Тулысынча уку → really has a stable, known probability of 1 in 30 and pays 35 to 1. The Kelly fraction is 0.57%: about $57 from a $10,000 bankroll. Under independent spinsматематикаБәйсез әйләнешләрТарихка карамастан, һәр әйләнешнең ихтималлыклары бертигез. Бу сайттагы һәр исәпләүнең нигезе.Тулысынча уку → and exact fractional staking, the geometric growth factor over 1,000 spins is about 1.7. Expected bankroll grows faster because rare large wins pull up the average. These are model calculations, not evidence that any named historical player used Kelly or achieved this result.
Гадәти һәм уртача
The gap between the typical bankroll and the average one is wide. Take a pocket that hits 1 time in 25, a hypothetical edge of 44% per unitакчаБерәмлекСистема яки уенчы эш итә торган төп ставка. Прогрессияләр теләсә кайсы өстәлдә кулланырлык булсын өчен берәмлекләрдә тасвирлана.Тулысынча уку → staked. Kelly stakes 1.26% of the bankroll on it. After 1,000 spins the typical bankroll has grown about 11.5 times, while the average, pulled up by a few very lucky runs, has grown about 249 times. Betting more than Kelly raises the average and lowers the typical result: at twice the Kelly stake the typical bankroll only doubles, and by two and a half times the Kelly stake it shrinks, although every bet still carries a 44% edge. In this example, half-Kelly retains about 78% of the expected log growth. This fraction depends on the probabilities and payout.
Өстенлек фараз булганда
Kelly uses the true probabilities, but a player usually has only estimates. Selecting the busiest pocket from a past record creates a selection problem: even a fair wheel has a busiest pocket. Its observed rate can overstate its future probability. Choosing the stake from that same record compounds the error. An independent follow-up sample helps test a proposed bias (see How to Detect Roulette Wheel Bias). Reducing the calculated fraction reduces exposure, but cannot turn a false edge into a real one.
Өстенлеге булган кешеләр
Haghani and Dewey (2016) studied 61 participants given $25 and 30 minutes to bet on a simulated coin with a disclosed 60% chance of heads. The payout cap was $250; its value was revealed when a proposed winning bet would reach it. Their reported 21% success category included balances of at least $200, while the 28% “bust” category meant less than $2, not necessarily zero. Eighteen participants bet their entire balance on one flip. The uncapped Kelly fraction is 20%, but the cap and deadline change the optimization problem. The experiment illustrates how stake choices matter even with a known advantage; it does not establish one best strategy for every objective.
Аның урынына нәрсә кулланырга
Өстенлек булмаганда ставка зурлыгы — үсеш мәсьәләсе түгел, бюджет мәсьәләсе: ставка = сез бер әйләнешкә тотарга әзер сумма, сәгатьлек бюджеттан һәм өстәлнең тизлегеннән чыгарыла (уен акчасы белән идарә итү бите). Келлиның гади уенчыга өлеше — җавабының ачыклыгы: нуль. Нульдән өстә куйган һәрнәрсә — уйнау бәясе, аны сез сайлыйсыз, ул бер формула белән дә оптимальләштерелми.
Өлешчә Келли һәм «акча белән идарә итү» турында искәрмә
Betting a fixed percentage of the current bankroll is proportional staking: the stake rises after wins and falls after losses. Flat bettingстратегияДаими ставкаҺәр әйләнештә бер үк сумманы кую. Һәр прогрессия чагыштырыла торган үлчәм.Тулысынча уку → instead keeps the cash stake fixed. Neither creates an edge on ordinary roulette. With infinitely divisible stakes and a fraction below 100%, proportional staking never reaches exactly zero in finitely many losses, but the balance can become arbitrarily small. Real table minimums can prevent further play much sooner. The growth-optimal fraction remains zero.
Формула
Сораулар
Only when the actual probabilities, payouts and conditions give a credible positive advantage. Standard bets on an unbiased wheel have no such advantage.
Using half the calculated fraction reduces exposure to errors in the estimated edge. The familiar three-quarters-growth rule is an approximation for small advantages, not a universal identity. It does not protect against an edge that does not exist.
Юк. Келли өстенлек булганда үсешне оптимальләштерә. Уен акчасы белән идарә итү өстенлек булмаганда чыгымнарны контрольдә тота.
Күңелле математика
Башта үзегез чишеп карагыз. Һәр чишелеш яшерелгән; әзер булгач ачыгыз.
Suppose a hypothetical bet on one number has a known 44% edge under standard payoutsакчаТүләүОткан ставка кайтара торган сумма, кире кайтарылган ставкага өстәп «X гә 1» дип күрсәтелә.Тулысынча уку → and independent spinsматематикаБәйсез әйләнешләрТарихка карамастан, һәр әйләнешнең ихтималлыклары бертигез. Бу сайттагы һәр исәпләүнең нигезе.Тулысынча уку →. Kelly gives a 1.26% bankrollакчаУен акчасыУен өчен аерып куелган гомуми сумма. Уен акчасы белән идарә итү — аның күпме өлешен бер ставкада һәм бер сессиядә куркыныч астына куярга карар итү.Тулысынча уку → fraction. What if the same 44% edge came on one bet spread over five neighboring numbers?
Чишелешне күрсәтү
Җавап Ул вакытта Келли уен акчасының 7,1% ын куша, һәм уен акчасы алты тапкырга диярлек тизрәк үсә: 1 000 ставкада якынча 1,25 миллион тапкыр, якынча 11,5 тапкырга каршы.
A straight upставкаБер санга ставкаБер сан, 35:1 түли.Тулысынча уку → with a 44% edge wins with chance 0.04, since 36 × 0.04 = 1.44. Kelly’s stake is the edge divided by the odds: 0.44/35 = 1.26%. The typical growth per bet is 0.04 × ln(1 + 35 × 0.0126) + 0.96 × ln(1 − 0.0126) ≈ 0.00244, so 1,000 bets multiply the bankroll by about e^2.44 ≈ 11.5.
Spread one stake over five numbers and the bet wins with chance 0.20 and pays 36/5 for 1, that is 6.2 to 1: still a 44% edge, since 0.2 × 7.2 = 1.44. Kelly’s stake becomes 0.44/6.2 = 7.10%, and the growth per bet 0.01404, about 5.75 times as much. Over 1,000 bets that is e^14.04, about 1.25 million.
The edge is the same; the swings are smaller. A bet that wins one time in five has a larger growth-optimal fraction in this model, although losses can still reduce the bankroll severely. This comparison assumes the same known edge for both bets; actual predictions need independent evidence.
Assume two numbers are adjacent on the betting layoutҗиһазӨстәлӨстәлдәге басылган ставкалар челтәре. Шулай ук: өстәл, сукно, тукыма.Тулысынча уку → and each has a stable, known probabilityматематикаИхтималлыкНәтиҗәнең мөмкинлеге, 0 дән 1 гә кадәр яки 0% тан 100% ка кадәр. Бер сан: 1/37 = 2,70%.Тулысынча уку → of 1 in 25 on independent spins. Compare a splitставкаИке санга ставкаЯнәшә ике сан, 17:1 түли.Тулысынча уку → between them at 17 to 1 with equal straight-up stakes on the two numbers. How much does Kelly say, and how fast does the bankroll grow compared with one such pocketҗиһазУячРоторда номерланган 37 бүлекнең берсе. Шулай ук: ячейка, касәчек.Тулысынча уку →?
Чишелешне күрсәтү
Җавап Аермасы юк: ике санга ставкага уен акчасының 2,59% ы, яки һәр санга 1,29%. Типик уен акчасы 1 000 әйләнештә якынча 155 тапкыр үсә, бер уяч белән 11,5 тапкырга каршы.
The split wins with probability 2/25 = 0.08 and pays 17 to 1, so it returns 18 × 0.08 = 1.44 per unitакчаБерәмлекСистема яки уенчы эш итә торган төп ставка. Прогрессияләр теләсә кайсы өстәлдә кулланырлык булсын өчен берәмлекләрдә тасвирлана.Тулысынча уку → staked: an edge of 44%, the same as one biased pocket. Kelly’s stake is the edge divided by the odds: 0.44/17 = 2.59%.
Two straight-up bets of 1.29% each give exactly the same results. When either number comes up, one chipакчаФишкаБилгеле сумманы аңлатучы жетон, ставка ясау өчен өстәлгә куела. Шулай ук: check.Тулысынча уку → wins 35 to 1 and the other is lost, a net of 34 × 1.29% = 44% of the bankroll, as the split pays; when neither does, both are lost.
The growth per spin is 0.00505, against 0.00244 for one pocket, so over 1,000 spins the typical bankroll grows e^5.046 ≈ 155 times rather than e^2.44 ≈ 11.5 times. The geometric growth factor is larger because the combined bet wins more often at the same 44% edge. It is a model result, not a guaranteed bankroll.
Көлке өчен тәнәфес
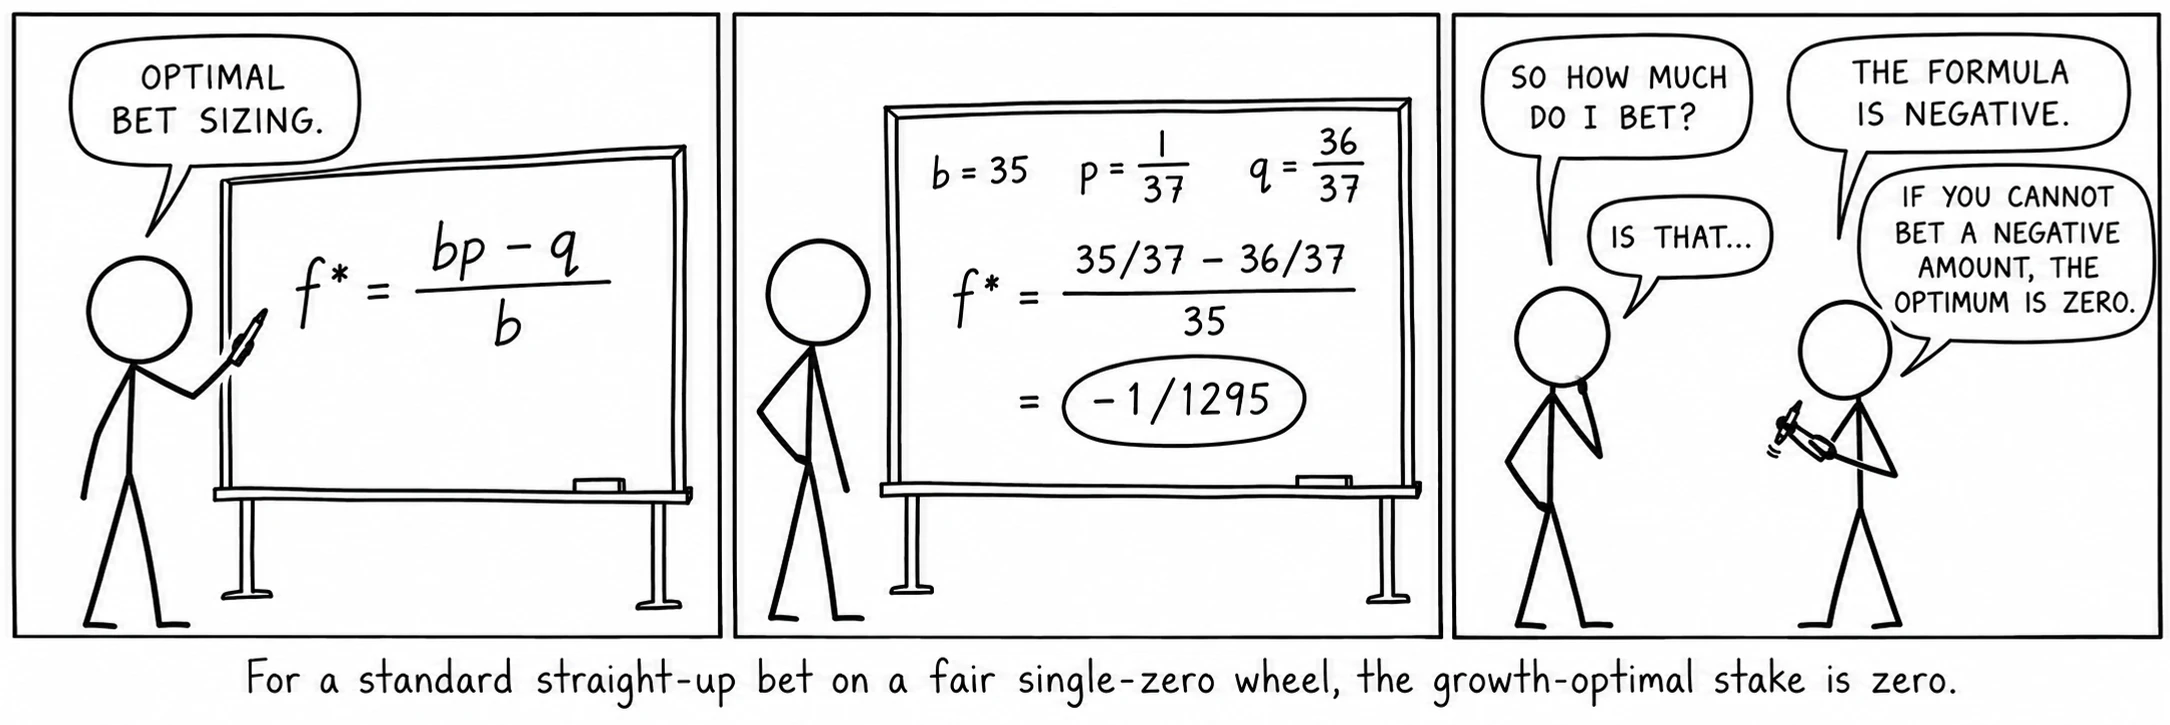
Рулеткада үсеш өчен оптималь ставка — һәркем белгән сан.
Чыганаклар
- Kelly, J. L. “A new interpretation of information rate.”
- Breiman, L. “Optimal gambling systems for favorable games.”
- Thorp, E. O. “Optimal gambling systems for favorable games.”
- Thorp, E. O. The Mathematics of Gambling.
- Epstein, R. A. The Theory of Gambling and Statistical Logic, 2nd ed.
- Taylor, D. G. Games, Gambling, and Probability: An Introduction to Mathematics, 2nd ed.
- Ethier, S. N. The Doctrine of Chances: Probabilistic Aspects of Gambling.
- Haghani, V. & Dewey, R. “Rational decision-making under uncertainty: observed betting patterns on a biased coin.”